.jpeg)
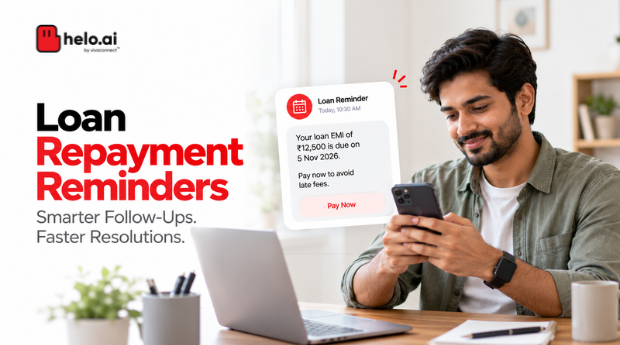


For lenders, a missed repayment does not always mean a borrower is unwilling to pay. A reminder may have gone unnoticed, a transaction may have failed, or the borrower may need clarification about the amount due.
Banks, NBFCs and fintech lenders can use digital channels to make repayment communication more timely and accessible. But sending more messages is not the same as resolving the problem. Effective communication needs to help borrowers understand what is due, take the next step and get assistance when something goes wrong.
Research and regulatory guidance point to two important considerations: communication should help borrowers act, and recovery processes must protect their privacy and dignity.
1. Before the due date: make repayment easier to act on
A repayment reminder is most useful when the borrower can quickly understand what needs to be done.
Lenders can use channels such as SMS, email, mobile app notifications and other approved messaging channels to communicate upcoming instalments. A useful reminder should make the due date clear, identify the lender, explain the amount due where appropriate, and direct the borrower to an authorised payment route.
For example, a pre-due reminder could help a borrower confirm the upcoming instalment and find the lender's official payment option without having to search through previous messages or documents.
The communication should also account for what happens next. If a payment is completed, the borrower should be able to access confirmation through the lender's established process. If the payment does not go through, the next communication should help them understand how to check the status or seek assistance.
The practical takeaway: A reminder should reduce uncertainty, not simply add another notification to the borrower's phone.
2. After a missed payment: focus on the reason and the next step
When a repayment is missed, repeatedly sending the same message may not address the underlying issue.
The borrower may have encountered a failed transaction, may be unsure whether a previous payment was received, or may need help understanding the outstanding amount. Each situation calls for a different response.
A more useful follow-up process can distinguish between these needs:
- Payment status: Help the borrower check whether a transaction was successful or is still being processed.
- Outstanding dues: Direct the borrower to the appropriate account statement or repayment details.
- Payment difficulty: Provide a clear route to the lender's authorised support team.
- Disputed payment: Make it possible to raise the issue and have it reviewed through the lender's established process.
This is where the quality of follow-up matters. Research from J-PAL on relationship banking in India examined 1,319 borrower accounts and found that borrowers assigned personal relationship managers had better repayment behaviour. The study did not test automated digital reminders, but it highlights a relevant distinction: how lenders engage with borrowers can matter, not just whether contact takes place. In J-PAL's summary, borrowers who received only a reminder call before due dates showed no significant drop in late payments. Read the J-PAL research.
Digital channels can help make routine follow-up more consistent. They should also provide a way to reach a person when an automated response cannot resolve the issue.
The practical takeaway: After a missed payment, move from repeating the reminder to helping the borrower understand and resolve the problem.
3. Borrower queries: connect communication with support
Repayment-related questions can be straightforward, but they still need clear answers. Borrowers may want to know whether a payment has been received, how much remains outstanding, where to find a statement or how to raise a dispute.
Digital channels can help lenders direct these queries to the right place. Routine requests may be handled through established self-service options, while account-specific problems or complaints should reach the appropriate support team.
The handoff is important. A borrower who reports a failed payment should not be sent through a generic sequence of reminders without a clear way to get the issue reviewed.
The Reserve Bank of India's Digital Lending Directions, 2025 include provisions covering loan servicing and repayment, borrower data and grievance redressal. They also make clear that a regulated entity remains responsible for its obligations when it works with a lending service provider. Para 9 also requires repayments to flow directly to the lender's bank account, not through a lending service provider.
For lenders, this makes ownership of the customer issue an important part of the communication process. A digital interaction should help the borrower reach the responsible organisation and its established grievance mechanism when needed.
The practical takeaway: A digital channel is useful only if the borrower can get from a question to a reliable answer.
Connecting reminders, queries and support? Read Helo.ai's Enterprise Playbook for AI-led customer engagement.
4. Responsible recovery must guide every channel
Repayment communication involves more than delivery and timing. It also involves how often a borrower is contacted, what information is shared, who is contacting them and how complaints are handled.
The RBI's Digital Lending Directions, 2025 address customer protection, data privacy and grievance redressal in digital lending. Lenders should ensure that their own communication processes and any third-party arrangements follow the requirements applicable to them.
There is also an important regulatory development for NBFCs. The RBI issued the Non-Banking Financial Companies -- Responsible Business Conduct (Third Amendment) Directions, 2026 on 6 August 2026, with the directions scheduled to take effect from 1 January 2027. The requirements apply to NBFCs within the directions' scope and include provisions on recovery-agent communication and conduct.
Among other requirements, the directions address prescribed contact hours, advance communication about recovery-agent details before a first in-person visit, records of recovery calls and safeguards against harassment or excessive communication. The precise obligations and applicability should be checked against the directions themselves and the lender's regulatory category. In the directions, agents may contact borrowers only from 8:00 am to 7:00 pm unless asked otherwise. Call records are kept for six months.
These requirements reinforce a broader operational principle: digital systems should help lenders maintain clear, accountable communication rather than simply increase the volume of collection messages.
The practical takeaway: Responsible follow-up is part of the repayment process, not a separate consideration to address later.
5. Bringing repayment communication into the wider customer journey
Repayment reminders, missed-payment follow-ups and borrower queries are often treated as separate activities. But from the borrower's perspective, they are connected parts of the same relationship with the lender.
A reminder may lead to a payment. A failed transaction may lead to a query. A query may require support or a complaint to be raised. If these interactions are disconnected, borrowers may have to repeat information or struggle to understand what happens next.
This creates an opportunity for lenders to think about communication as a connected journey, with clear next steps and appropriate routes to assistance at each stage.
Helo Clarity brings customer engagement and communication journeys together, helping businesses create more connected interactions across the customer lifecycle. For lenders, this provides a way to approach repayment communication as part of the wider customer journey, rather than as isolated messages. Helo Clarity unifies customer behaviour data into a single profile, segments customers and sends event-triggered messages across channels.
The focus is on making interactions more relevant and consistent, while lenders retain responsibility for repayment decisions, recovery procedures, customer protection and regulatory compliance. Specific channel availability, integrations and workflows should be confirmed against the current product scope before publication.
Planning repayment communication for your lending business? Talk to the Helo.ai team about SMS, WhatsApp and voice follow-ups.
The way forward
Digital channels can help lenders communicate before a due date, guide borrowers after a missed payment and make it easier to raise repayment-related questions. But the value lies in what happens after the message is sent.
A clear reminder, a useful next step and a reliable route to support can make repayment communication easier to navigate. When these interactions are connected and responsibly managed, lenders can improve the communication process without losing sight of borrower protection.
The goal is not simply to contact borrowers more often. It is to make every interaction clearer, more useful and easier to resolve.
Frequently asked questions
What should a loan repayment reminder include?
The due date, the lender's name, the amount due where appropriate and an authorised payment route.
Do digital repayment reminders improve repayment?
The evidence is limited. J-PAL's India study found that personal relationship managers improved repayment, but a reminder-only call showed no significant drop in late payments. The study did not test automated digital reminders.
What do RBI's NBFC rules say about recovery calls?
From 1 January 2027, the Third Amendment Directions, 2026 limit recovery-agent contact to 8:00 am to 7:00 pm unless the borrower asks otherwise. They also require call records to be kept for six months.