

A borrower starts a loan application on their phone. They enter their details, upload documents and wait for a decision. The loan may be approved, but the money does not arrive. Or the borrower leaves before submitting the application.
For banks, NBFCs and fintech lenders, these outcomes raise different questions. Did the borrower encounter a technical problem? Were they waiting for a decision? Did they decide the loan was no longer right for them?
Each situation calls for a different response. Treating them all as lost conversions can lead lenders to fix the wrong problem.
Research into digital lending apps in India offers clues about parts of the borrower experience that deserve attention. However, it does not establish a single drop-off rate for the wider lending industry.
What does the research reveal about the lending journey?
A study published in Frontiers in Artificial Intelligence in January 2026 analysed 15,408 user reviews across seven RBI-approved peer-to-peer lending platforms in India.
The researchers classified 55% of evaluations as positive, 41% as negative and 4% as neutral. Positive feedback included loan disbursement, withdrawals and EMI payments. Negative feedback highlighted interface design, transparency around rejections and login functionality.
Source: Frontiers in Artificial Intelligence, User Perceptions of RBI-Approved P2P Digital Lending Apps
These findings point to several areas worth investigating. A borrower may struggle to use an app, have difficulty accessing an account or feel unclear about a lending decision.
But online reviews cannot show how many applicants abandoned a loan, how many were declined or how many approved loans never reached disbursement. The study also covers seven P2P lending platforms, not the entire banking, NBFC and fintech market.
The findings are therefore useful signals about customer experience, not industry-wide conversion benchmarks.
Where can borrowers leave the journey?
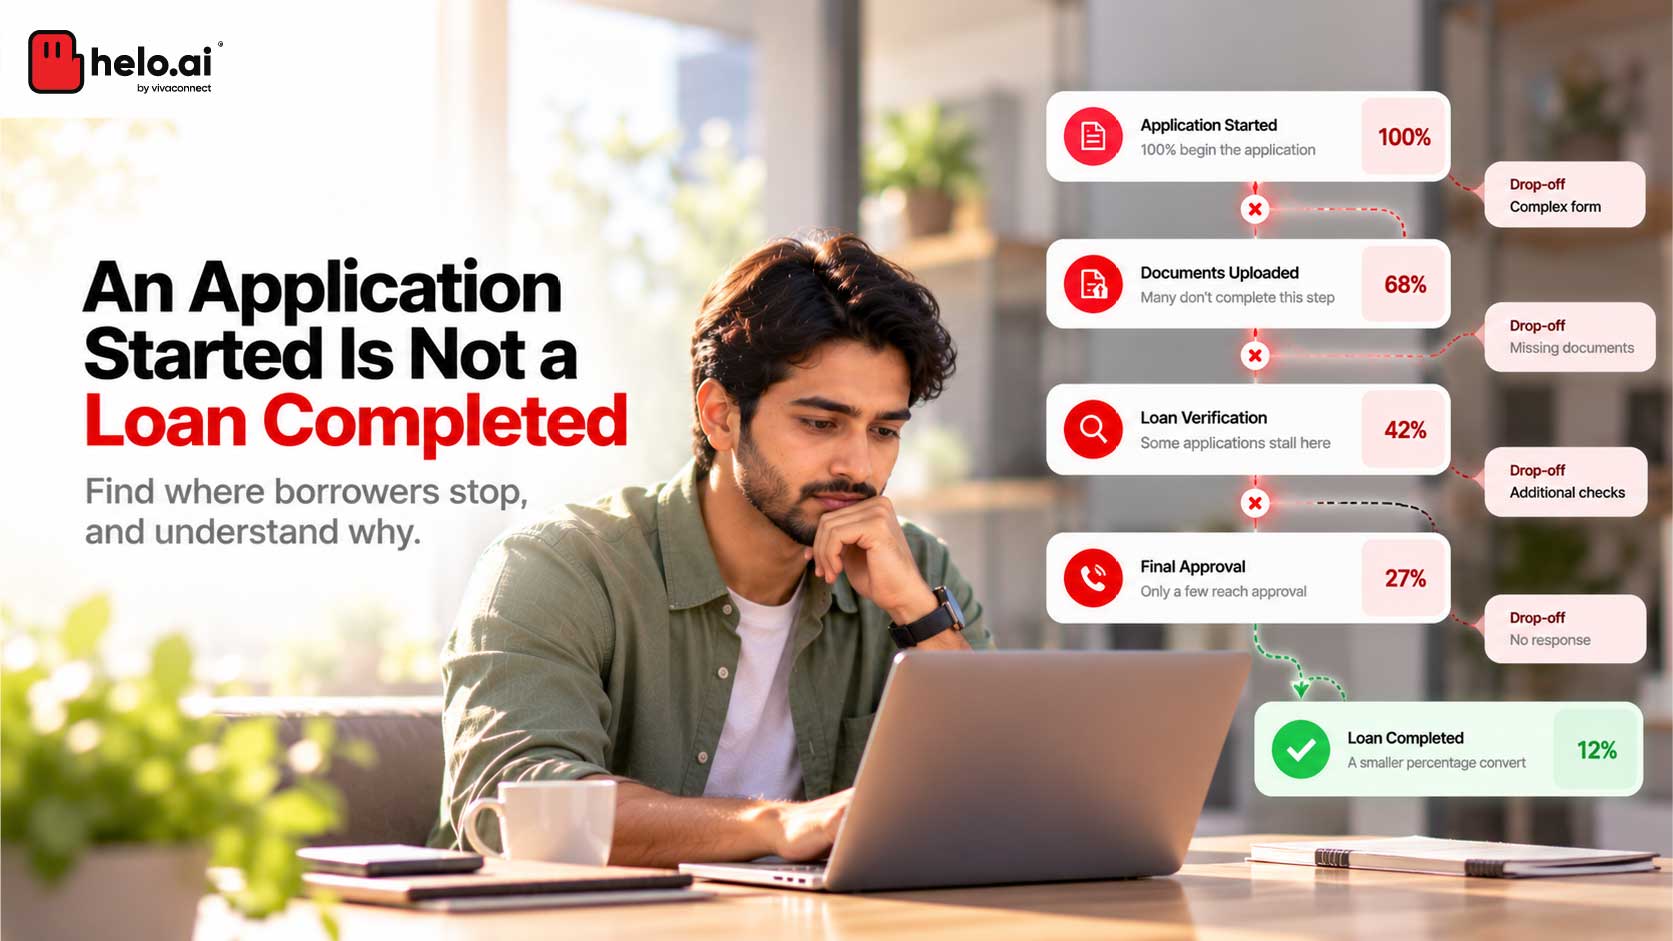
Borrowers can leave at three points: during the application, during assessment and approval, and after approval but before disbursement. Each stage has different requirements. Looking at them separately helps lenders understand what is happening instead of treating every incomplete loan as the same problem.
1. During the application: when the process becomes difficult
A borrower may start with the intention of taking a loan but leave before submitting the application.
Possible issues include lengthy forms, repeated login attempts, document upload errors or uncertainty about what information is required. These are potential causes to investigate, not reasons that can be assumed for every incomplete application.
The lending app study identified interface and login functionality among the areas receiving negative feedback. It did not measure how often those issues led to abandonment.
What lenders should examine: Track applications started, each step completed and applications submitted. Break the results down by device, error type, repeat attempts and application stage. This can help reveal where borrowers are having difficulty.
2. During assessment and approval: when the decision is unclear
Submitting an application does not guarantee approval. Lenders must assess creditworthiness, verify information and apply their lending criteria.
Some applicants may be declined. Others may need to provide additional information, while some applications may remain pending.
The distinction matters. A legitimate credit decision is not the same as an application that stalled because a verification step failed. The study's findings on transparency around rejections make decision communication worth examining, but they do not establish how frequently unclear decisions cause borrowers to leave.
What lenders should examine: Review pending applications, verification failures, time to decision, decisions communicated and the next steps taken by applicants. Record declines separately from incomplete applications and technical failures.
3. After approval: when the loan does not reach disbursement
An approval does not automatically mean the borrower will receive the funds. The borrower may still need to review the offer, understand the costs, accept the terms and complete the required steps.
Some borrowers may decide the loan is not suitable. Others may encounter a process issue or need clarification before proceeding.
The Reserve Bank of India's Digital Lending Directions, 2025 set out requirements relating to creditworthiness, disclosures, disbursement, servicing and the cooling-off period. These make the steps between approval and disbursement important to examine.
What lenders should examine: Track offers issued, offers accepted, agreements completed, disbursements initiated and funds successfully credited. Record the time between each step and the reason a disbursement remains incomplete.
Why one overall conversion rate is not enough
Suppose a lender finds that many applications do not result in a disbursed loan. That figure alone cannot explain what needs to change.
Some applicants may not meet the lender's eligibility criteria. Others may struggle to complete the process. Some may receive an offer but decide its terms do not suit them.
Each outcome has a different implication. Simplifying a form will not change a credit decision, and sending more reminders will not necessarily resolve confusion about loan terms.
A more useful approach is to measure each stage and record why borrowers do not move forward.
Stage | What to measure | What it can reveal |
Application started | Applications started versus submitted | Where borrowers stop before submission |
Information and verification | Completion, errors and pending documents | Where the process becomes difficult |
Credit assessment | Decisions, pending cases and time to decision | Whether cases await information or a decision |
Offer and acceptance | Offers issued versus accepted | Whether borrowers proceed after reviewing terms |
Disbursement | Accepted loans versus funds credited | Where approved loans remain incomplete |
This is a measurement framework lenders can apply to their own data, not a set of industry-wide benchmarks. Each stage rate is the number that moved on divided by the number that entered it, for example funds credited divided by accepted loans.
What should lenders change first?
The first step is to identify the problem at each stage. Once lenders understand where borrowers are struggling, they can make changes that address the actual cause.
Make applications easier to complete. Review form length, login issues, document requirements and errors. Tell borrowers what information is needed before they reach a step they cannot complete.
Make decisions and next steps clear. When an application needs more information or a decision has been made, communicate the status and explain the next action where appropriate. Clear communication should never imply that approval is guaranteed.
Make loan terms understandable. Borrowers need to understand the loan amount, repayment obligations, costs and terms before accepting. RBI's Digital Lending Directions include requirements for a Key Facts Statement and other borrower disclosures.
Follow up when appropriate. Where permitted, reminders can help borrowers who intended to continue but left a step unfinished. Messages should reflect the actual application status and should not pressure borrowers into taking credit they do not need.
Measure the effect of changes. If a lender simplifies a form or improves status updates, compare completion rates and processing times before and after the change. Also track errors, complaints and application quality. A higher completion rate alone does not prove that lending outcomes have improved.
Measuring borrower reminders and status messages? The free CPaaS KPI Handbook explains 50+ WhatsApp, SMS and RCS metrics with formulas and worked examples.
The evidence lenders still need
Published research can highlight problems with usability, access and decision transparency. To understand where borrowers are actually dropping out, lenders need to examine their own application and loan records.
That means connecting application events, verification results, credit decisions, offer acceptance and disbursement records. It also means recording consistent reasons for abandonment, rejection, pending cases and technical failures.
With that information, lenders can distinguish between three questions: where borrowers stop, why they stop and which changes make a measurable difference.
The aim is not simply to push more applications through to disbursement. It is to make the process clear and reliable for eligible borrowers while keeping credit decisions responsible.
The most useful drop-off metric is not just where borrowers leave. It is whether the lender understands why, and can act on that evidence.
Want clearer status updates for borrowers? Talk to the Helo.ai team.
Frequently asked questions
What is drop-off in digital lending?
Drop-off is when a borrower leaves a digital loan journey before disbursement. It can happen during application, assessment, offer acceptance or payout, so each stage needs separate measurement.
Why do approved loans not reach disbursement?
After approval, a borrower may decide the terms do not suit them, need clarification or hit a process issue. Lenders need stage-level records to tell which.
What do RBI's Digital Lending Directions, 2025 require lenders to disclose?
The Directions, dated 8 May 2025, require regulated lenders to give borrowers a Key Fact Statement. They also give borrowers a no-penalty exit during a cooling-off period of at least one day.